
JPMorgan analyst Doug Anmuth projects Amazon’s capital spending will reach $395 billion in 2027 and $476 billion in 2028, far above the roughly $220 billion the company expects this year. The forecast follows CEO Andy Jassy’s pledge to spend “meaningfully more” next year. Amazon’s trailing 12-month free cash flow has already swung to a $42.4 billion outflow, driven by a $94.8 billion increase in property and equipment purchases tied largely to AI. AWS revenue rose 39.3% to $46 billion in the third quarter, with a backlog of $578 billion, as Jassy targets more than 40% growth in 2027 and 2028 and a trillion-dollar cloud business within five to 10 years. Analysts are split on the risk.
Amazon’s capital spending is poised to climb far beyond the roughly $220 billion the company has penciled in for 2026, with JPMorgan projecting the bill will approach half a trillion dollars annually within two years.
In a research note, JPMorgan technology analyst Doug Anmuth estimated capital expenditures of $395 billion in 2027, a 77% jump from the prior year, followed by $476 billion in 2028, up another 20%. “We do not expect capex growth to decelerate or slow next year,” Anmuth wrote. He added that management’s clear view of demand gives it the confidence to commit to growth above 40% over the next two years and to push even harder into AI compute infrastructure.
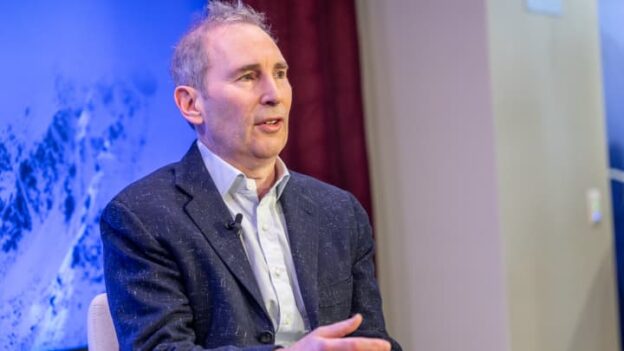
The forecast follows comments from Amazon CEO Andy Jassy, who said last week that the company would spend “meaningfully more” in 2027 without attaching a figure. Anmuth’s note supplies one.
The scale of the outlay is already visible in Amazon’s cash flow. Free cash flow swung to an outflow of $42.4 billion over the trailing 12 months, compared with an inflow of $14.8 billion in the same period a year earlier. The reversal was driven mainly by a $94.8 billion year-over-year increase in purchases of property and equipment, which Amazon attributed largely to AI investments.
| Metric | Trailing 12 months to Sept. 30, 2025 | Trailing 12 months to Sept. 30, 2026 |
|---|---|---|
| Free cash flow | $14.8 billion inflow | $42.4 billion outflow |
| Year-over-year increase in property and equipment purchases | — | $94.8 billion |
| Estimated 2026 capital spending | — | $220 billion |
| JPMorgan 2027 capex estimate | — | $395 billion (+77% YoY) |
| JPMorgan 2028 capex estimate | — | $476 billion (+20% YoY) |
Note: Capital spending figures for 2027 and 2028 are JPMorgan estimates; the 2026 figure is Amazon’s own projection.
The third quarter itself carried a $75.9 billion capital bill. Results fell just short of estimates on both revenue and earnings per share, and the stock dropped more than 6% in after-hours trading before recovering. Shares were down more than 1% on Friday but rebounded the following Monday, lifting the year-to-date gain to 9%, trailing the S&P 500’s 11% advance.
AWS carries the growth story
The cloud unit remains the strongest part of the business. Amazon Web Services revenue rose 39.3% from a year earlier to $46 billion, the sixth consecutive quarter of accelerating growth, and now runs at an annualized pace of about $184 billion. Operating income for the segment reached $17.8 billion, edging past Wall Street’s forecast of roughly $45.6 billion in revenue. The backlog stood at $578 billion, growing at a triple-digit rate, and Jassy described it as well diversified.
Jassy has argued that about 85% of global IT spending still sits on premises and that much of it should migrate to the cloud over the next decade. He said Amazon is installing an AI accelerator roughly every 14 seconds, with customers absorbing capacity nearly as fast as it comes online. “Almost as fast as we install capacity, customers are gobbling it up,” he said on the earnings call.
CFO Brian Olsavsky said the AI investments have the potential to generate long-term revenue and free cash flow. Jassy said Amazon keeps shortening the payback period on its infrastructure, though returns differ between the core cloud business and the AI build-out, and that a large block of capacity is due over roughly the next eight quarters. He sees AWS growing more than 40% in both 2027 and 2028 on the way to becoming a trillion-dollar revenue business within five to 10 years, and said Amazon could end up with two such businesses, with online stores as the other candidate.
The debate over the bill
Not everyone is comfortable with the pace. Bank of America flagged rising capital spending as a risk for Amazon while noting that results should show strong returns on the capacity being added. Morgan Stanley’s Brian Nowak is more optimistic, projecting AWS growth of 47% in 2027 and 42% in 2028, with a $350 price target on the stock.
Earlier in the year, Citi and JPMorgan raised their price targets as AWS growth picked up, pointing to Amazon’s custom Trainium and Graviton chips, which were reportedly generating more than $10 billion a year, and to partnerships with Anthropic and OpenAI as a boost for the cloud unit.
Amazon is not alone in absorbing the cash hit. Alphabet posted negative free cash flow of $9.1 billion in the third quarter after spending about $51.4 billion on capital projects, even as Google Cloud revenue more than doubled. Amazon founder Jeff Bezos, speaking at Italian Tech Week in October 2025, likened AI to an industrial bubble in which separating strong bets from weak ones is genuinely difficult for investors, while remaining optimistic about the technology itself.
The concern among investors is that eventual AI revenue may not justify the spending, making them warier of the cloud giants leading the build-out. Amazon stock trades at about 30 times forward earnings estimates and sits roughly 14% below its August high.
For the market, the JPMorgan note reframes the question from whether Amazon will spend heavily to how long the spending curve keeps steepening. A $476 billion annual outlay would make Amazon one of the largest single sources of AI infrastructure demand, with consequences for chip suppliers, data center developers and power providers, while putting free cash flow under pressure for years. Investors who once treated Amazon as a cash-generating machine now have to underwrite a multiyear investment cycle whose payoff depends on AWS sustaining growth rates above 40%.
https://finance.biggo.com/news/4378b2d1-8eb8-41ba-9246-511b9ff9230c?shem=aimgspe,
