
This article first appeared on GuruFocus.
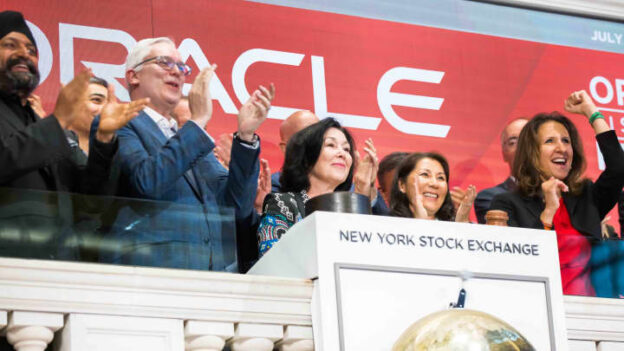
Oracle (NYSE:ORCL), the database and AI-cloud infrastructure provider, reported more than $30 billion of fresh AI-cloud contracts during its fiscal first quarter, adding another huge block of demand to an already swollen backlog. Shares gained approximately 1.3% to $149.47. The valuation picture is striking: Oracle trades 22.15% below its GF Value estimate of $191.99, suggesting the market is still discounting how efficiently the company can turn its AI backlog into cash.
The headline numbers are massive. Remaining performance obligations climbed to $664 billion, while cloud infrastructure revenue surged 121% to $7.4 billion. Oracle also added 850 megawatts of data-center capacity and delivered more than 300,000 GPUs. Yet there is a sharp counterweight to all that growth: quarterly free cash flow remained roughly $5 billion negative as the company poured capital into the infrastructure required to serve those contracts.
That tension is now the Oracle story. Its $664 billion backlog is more than 34 times quarterly revenue of $19.35 billion, giving the company extraordinary visibility into future demand. But backlog is not cash in the bank. Oracle still has to bring capacity online fast enough, finance an enormous infrastructure buildout and preserve attractive margins as AI workloads scale. If execution catches up with the contract book, today’s valuation gap could become increasingly difficult for investors to ignore.
https://finance.yahoo.com/technology/ai/articles/oracle-gains-while-664-billion-185423274.html?shem=aimgspc,
